
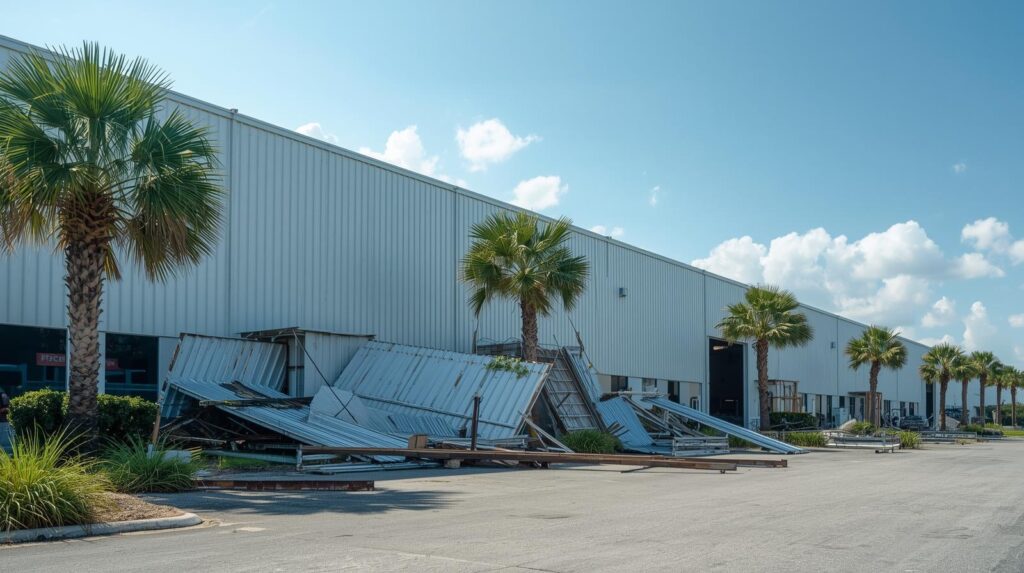
Warehouse Wind Damage Claims in Florida
Wind on a warehouse roof becomes a water-and-inventory loss the carrier tries to shrink
A large-span roof is a warehouse’s weak point: once wind lifts the membrane or panels, water reaches racking and stored goods, and the inventory loss can dwarf the structural repair. Add code upgrades that big commercial roofs trigger on rebuild, plus business interruption while operations are down, and the covered loss is far larger than the carrier’s first scope — which typically treats it as a simple roof patch. That is exactly the gap we close.
Florida property insurance claims: the deadlines and the fee cap
- Notice of a claim
- Under Fla. Stat. §627.70132, a property insurance claim or reopened claim is barred unless notice was given to the insurer within 1 year after the date of loss. A supplemental claim is barred unless notice was given within 18 months after the date of loss. — Fla. Stat. §627.70132(2)
- Time to bring a court action
- An action for breach of a property insurance contract must be brought within 5 years, running from the date of loss. This is a separate clock from the notice deadline, and §627.70132(5) states that the notice statute does not affect it. — Fla. Stat. §95.11(2)(e)
- What a public adjuster may charge
- A public adjuster’s compensation is capped at 20 percent of the amount of insurance claim payments or settlements, exclusive of attorney fees and costs, paid to the insured by the insurer. For claims based on events that are the subject of a declaration of a state of emergency by the Governor the cap is 10 percent, and that limit applies to claims made during the year after the declaration of emergency. — Fla. Stat. §626.854(11)(b)
- Which deadline applies to you
- Which of these applies to your claim depends on your policy and your date of loss.
Public Loss Adjusters, LLC — Robert Mack, Florida public adjuster, Lic. #A161638. The review is free and carries no obligation. Call 352-353-4556.
Florida’s climate exposes warehouses and industrial properties to frequent high winds, hurricanes, and tornadic gusts. Even minor structural failures can interrupt operations, damage inventory, and jeopardize long-term leases. Public Loss Adjusters, LLC represents commercial property owners, logistics firms, and tenants throughout Florida to evaluate, document, and recover from wind-related losses under property and business-interruption coverage. All warehouse wind damage claims we manage complies with §626.854 and §627.70131, Florida Statutes, ensuring lawful representation and timely carrier response.
Why Warehouse Claims Require a Distinct Approach
Warehouse buildings are often large-span metal structures that experience unique types of wind damage — roof panel uplift, fastener failure, or compromised insulation. Unlike small commercial offices, these facilities contain high-value inventory and sensitive machinery that can be exposed to rainwater intrusion. We treat every wind loss as both a structural and operational claim, ensuring all repair and downtime components are fully documented and reimbursed.
Our team establishes what actually caused the damage, which is the point the carrier will contest first.
Common Types of Warehouse Wind Damage
- Roof uplift and panel displacement — fasteners pulled loose or flashing separated, allowing water intrusion.
- Overhead door and dock seal failure — wind pressure causes frame misalignment and operational shutdown.
- Structural racking collapse due to roof leaks or ceiling movement.
- Water damage to stored goods after compromised roof systems or skylights.
- Electrical and HVAC failures caused by power surges or mechanical damage.
Challenges We Overcome
- Damage to roof and wall panels is frequently invisible from ground level, which is why a loss that looks minor from the car park often is not.
- Whether a repair or a replacement is the honest answer is an argument with evidence behind it, and it is one we make on your behalf.
- Ordinance & Law disputes: Florida Building Code revisions may require improved anchoring systems or impact-resistant materials. We ensure these costs are included under your Ordinance & Law endorsement.
- Inventory contamination: Wind-driven rain can introduce moisture and corrosion. We document each affected pallet, serial number, or equipment unit for inclusion in your contents claim.
- Operational downtime: Warehouse access restrictions, safety inspections, and temporary relocations can all trigger business interruption coverage.
Our Step-by-Step Process
- Initial Site Evaluation: We inspect all structural components — roof, siding, loading docks, and skylights — capturing photos and video documentation immediately after the event.
- Policy Review & Strategy: We identify applicable endorsements such as Windstorm or Hurricane Deductibles, Ordinance & Law, and Business Interruption coverage. We also determine whether concurrent causation applies.
- Engineering & Cost Estimating: Using independent engineers and Xactimate estimators, we quantify structural, mechanical, and electrical damages with precision line-item detail.
- Inventory & Contents Documentation: We coordinate physical counts and damage valuation for stored goods, machinery, and office equipment.
- Claim Presentation & Negotiation: We submit formal estimates, engineer reports, and recovery calculations directly to the insurer and monitor statutory response deadlines under §627.70131.
Mitigating Downtime and Protecting Operations
Every day your warehouse remains closed impacts clients and logistics partners. We assist in setting up temporary operations, coordinating emergency roofing, and securing equipment to prevent further loss. These mitigation costs often qualify as reimbursable “extra expenses.” We track them carefully and present a structured financial report supporting payment under your business interruption coverage.
Business Interruption for Warehouses
Interrupted trading is the part of a warehouse loss most often left out altogether, because none of it is visible on site. Whether it belongs in yours depends on the policy you hold. Call 352-353-4556.
Statutory Rights and Deadlines
Under §627.70131, insurers must acknowledge claims within 7 days and issue payment or denial within 60 days unless external conditions prevent it. Public Loss Adjusters, LLC ensures all correspondence is documented and that your claim proceeds lawfully and efficiently. We maintain a full compliance log ready for Department of Financial Services review or mediation if necessary.
⏰ Underpaid or closed out on a past commercial claim? Florida law may still give you a window.
Separate from the §627.70131 response deadlines, Fla. Stat. 627.70132 gives a policyholder a running window to reopen or supplement a property claim. The clock starts on the date of loss, not the day you discover the shortfall — so on older hurricane and water losses you may have far less time than you think.
Your policy’s own notice terms can be shorter, and every claim is different. Whether a past loss can still be reopened — and what the carrier left unpaid — is exactly what we assess. Call 352-353-4556.
General information about Florida claim deadlines under Fla. Stat. 627.70132, not legal advice. Windows run from the date of loss and vary by claim and policy; your policy’s prompt-notice terms may be shorter — contact us to confirm specific deadlines.
Questions we get about warehouse wind claims
The roof held. Why is there a claim at all?
Because wind damage on a large roof is often invisible from the ground and from the floor, and what it lets in afterwards lands on inventory and racking rather than on the structure. A loss described as a roof question tends to be settled as one. One call is how you find out: 352-353-4556.
Our stock was damaged but the building barely was. Is that one claim or two?
That is exactly the question that decides the number, and it is answered differently by different policies. Which way yours reads is worth knowing before anything is agreed. Call 352-353-4556 and we will tell you.
The insurer’s adjuster has already been out. Is it too late to get help?
Usually not, and this is the most common reason people wait too long. An adjuster having visited is not the same as the loss having been fully described, and what was written down that day tends to become the version of events everyone argues from afterwards. Whether anything can still be done depends on your policy and where the claim has got to. Call 352-353-4556 and we will tell you.
Our contractor’s number and the insurer’s number are a long way apart. Which one is right?
Neither, on its own. They are answers to two different questions, priced off different assumptions, and the gap between them is not usually about arithmetic. Working out which parts of that gap are arguable is the job, and it is not something to guess at from a spreadsheet. One call is how you find out: 352-353-4556.
What does this cost us?
The review costs nothing and carries no obligation. If we take the claim, the fee is a percentage of the claim payment and is capped by Fla. Stat. 626.854 — 20% ordinarily, and 10% for a claim arising from a declared state of emergency within the first year. No recovery, no fee. Call 352-353-4556 and we will tell you.
All commercial property damage · Hotel & hospitality · Office · Multi-family · Condo/HOA · Business interruption · Water · Fire · Appraisal & mediation
Notice: This page provides general information for Florida policyholders and does not constitute legal advice. Public Loss Adjusters, LLC, License A161638. Consistent with §626.854 and timelines under §627.70131, Florida Statutes. Supporting documentation and exhibits are provided under separate cover upon request. Please confirm receipt in writing.
Talk to a Florida Public Adjuster
Public Loss Adjusters, LLC (License A161638). Statute-compliant representation under §626.854 and §627.70131, Florida Statutes.
PO Box 560404, Montverde, FL 34756 • 352-353-4556 • rmack@placlaim.com
Supporting documentation provided under separate cover upon request. Please confirm receipt in writing.
Request a Free Commercial Claim Review
Tell us about the loss and a licensed public adjuster will review your commercial claim — no cost, no obligation. We represent property owners, boards and managers, not the carrier, and we are paid only on what we recover.
This sits within our work on commercial property damage claims in Florida.